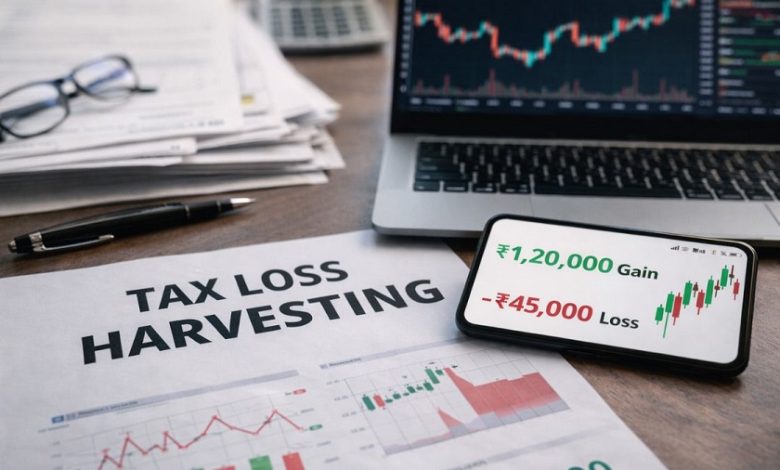
Market volatility is an inevitable part of investing, yet most portfolio owners treat unrealized losses as purely negative events. When market pullbacks push asset prices down, seeing red ink across a brokerage statement triggers instinctive frustration. Sophisticated investors, however, recognize that depreciated positions carry hidden financial utility. In a taxable investment account, paper losses can be converted into tangible economic value through tax-loss harvesting.
Tax-loss harvesting is the intentional practice of selling securities at a loss to offset realized capital gains elsewhere in your portfolio, reducing your immediate tax liability. Far from admitting defeat on an investment, harvesting losses is a systematic risk-management and tax-efficiency discipline. When executed with precision, it allows you to lower your annual tax bill, keep more working capital invested, and accelerate the compounding growth of your wealth over time.
The Core Mechanics of Matching Capital Gains and Losses
Federal tax law treats investment gains differently depending on how long you hold the underlying asset. Positions held for one year or less before being sold generate short-term capital gains, which are taxed at ordinary income tax rates reaching as high as 37 percent. Assets held for longer than one year qualify for long-term capital gains treatment, which commands preferential rates of 0, 15, or 20 percent, depending on your taxable income, alongside the potential 3.8 percent Net Investment Income Tax for high earners.
When you harvest losses, the internal revenue code requires you to follow a specific netting sequence:
-
Short-term capital losses must first offset short-term capital gains.
-
Long-term capital losses must first offset long-term capital gains.
-
If excess net losses remain in either category, they cross over to offset gains in the other category.
This ordering mechanism creates substantial opportunities for tax optimization. Because short-term capital gains face significantly higher tax rates than long-term gains, deploying harvested losses to eliminate short-term liability yields the highest immediate financial savings.
If your total harvested losses exceed your total capital gains for the calendar year, the remaining balance does not vanish. You can use up to $3,000 of net capital losses to offset ordinary income each year, or $1,500 if married filing separately. Any unused losses beyond that $3,000 threshold roll forward indefinitely into future tax years, creating a valuable reserve of tax deductions ready to shield future market profits.
Navigating the Wash-Sale Rule Without Sacrificing Exposure
The most critical regulatory hurdle in tax-loss harvesting is the wash-sale rule. Designed to prevent investors from claiming artificial tax deductions while maintaining an uninterrupted investment position, the rule disallows the loss deduction if you purchase a substantially identical security within a specific 61-day window. This window spans the 30 days prior to the sale date, the day of the sale itself, and the 30 days following the transaction.
If you violate the wash-sale rule, your realized loss is added to the cost basis of the newly acquired replacement shares rather than deducted on your current tax return. More critically, executing a wash sale across separate accounts—such as selling a stock at a loss in a taxable account and repurchasing it inside an Individual Retirement Account within 30 days—permanently forfeits the loss deduction without adjusting the basis inside the retirement account.
Preserving Asset Allocation Through Proxy Assets
Harvesting losses does not require you to sit in cash on the sidelines, risking missed market rebounds. The key to successful execution is replacing the sold asset with a correlated, yet not substantially identical, investment that preserves your intended portfolio allocation.
If you harvest a loss by selling an exchange-traded fund tracking the S&P 500, purchasing the identical ETF from a competing fund provider could trigger scrutiny. Instead, you can immediately rotate capital into a total stock market fund, a large-cap value index, or an ETF benchmarked against the Russell 1000. These funds share similar risk and return profiles, ensuring your capital remains fully exposed to an equity recovery while strictly adhering to regulatory guidelines. Once the 31-day cooling-off period concludes, you can rotate back into your primary holding if desired.
Shifting from Year-End Scrambling to Year-Round Execution
A common mistake among retail investors is treating tax-loss harvesting strictly as an annual December ritual. Waiting until late autumn to audit your taxable portfolio leaves significant money on the table. Market corrections and sector rotations do not follow a calendar schedule; severe drawdowns often occur in the spring or summer, only for markets to stage major recoveries before winter arrives.
By auditing your positions continuously throughout the year, you can capture temporary price dislocations as they happen. An investor who harvested losses during a brief mid-year market correction locks in deductions while buying into discounted proxy assets, riding the subsequent recovery upward. An investor who waited until December might find those same positions trading at a profit, missing the opportunity entirely.
Automated wealth platforms and direct indexing strategies have made continuous harvesting far more accessible. Direct indexing allows an investor to own hundreds of individual corporate equities rather than a single pooled index fund. Even when an overarching index trades flat or posts modest gains, individual component stocks within that index inevitably experience sharp pullbacks. Direct indexing enables the continuous harvesting of losses from underperforming individual equities while capturing the positive returns of the broader market.
The Strategic Balance: Tax Deferral Versus Permanent Benefit
To evaluate tax-loss harvesting accurately, you must understand what the strategy actually accomplishes. When you sell an asset at a loss and immediately purchase a replacement proxy, you reset your cost basis lower. If the market eventually appreciates, you will theoretically face larger capital gains down the road when you exit the replacement position.
In many scenarios, tax-loss harvesting operates as a tax-deferral mechanism rather than an outright tax elimination tool. However, deferral holds immense intrinsic value. Paying taxes years or decades into the future rather than today functions as an interest-free loan from the government. The money saved on this year’s tax return remains invested, compounding and generating returns for years.
Furthermore, several real-world circumstances convert this tax deferral into a permanent financial gain:
-
You may harvest losses against high ordinary income rates today and realize future long-term capital gains years later during retirement when your overall tax bracket is substantially lower.
-
You can donate appreciated replacement securities directly to qualifying charitable entities, bypassing capital gains taxes entirely while claiming a charitable deduction.
-
Under current federal estate guidelines, assets held until death receive a step-up in cost basis, which permanently wipes out all unrealized capital gains for your heirs.
Integrating Tax Efficiency into Broader Portfolio Management
Tax-loss harvesting should never override core investment principles. Selling a high-conviction asset simply to chase a small tax write-off makes little sense if transaction fees, wide bid-ask spreads, or tracking errors distort your long-term wealth strategy. The tax code should inform your portfolio management, not dictate it.
When applied thoughtfully within non-retirement accounts, tax-loss harvesting transforms unpredictable market downturns into an active portfolio advantage. By treating downward price volatility as an opportunity to generate tax alpha, you convert temporary market stress into lasting, compounding financial efficiency.